Inflation-Proof Your Savings: A 2026 Guide to 7% Growth
Advertisement
Inflation, the silent thief of wealth, continuously erodes the purchasing power of your hard-earned money. As we look towards 2026, the economic landscape continues to present challenges and opportunities for those aiming to safeguard and grow their assets. For many, the goal isn’t just to keep pace with inflation, but to outpace it significantly, aiming for a robust 7% annual growth on savings. This comprehensive guide will delve into actionable strategies to help you inflation proof savings and achieve this ambitious target, ensuring your financial future remains secure and prosperous.
Understanding inflation is the first step in combating its effects. Inflation is the rate at which the general level of prices for goods and services is rising, and consequently, the purchasing power of currency is falling. While central banks often target a 2% annual inflation rate, real-world experiences can vary significantly, impacting everything from daily groceries to long-term investments. Ignoring inflation is akin to letting a slow leak drain your financial bathtub; eventually, there will be nothing left. Therefore, actively working to inflation proof savings is not merely a good idea, but a financial imperative.
The 7% growth target by 2026 is ambitious but achievable with a disciplined approach and strategic asset allocation. This isn’t about chasing high-risk, speculative investments, but rather about building a resilient portfolio designed to thrive in various economic conditions. We will explore a mix of traditional and alternative investment vehicles, alongside smart financial planning techniques, all geared towards helping you inflation proof savings effectively.
Advertisement
The Core Principles of Inflation-Proofing
Before diving into specific investments, it’s crucial to understand the foundational principles that underpin successful strategies to inflation proof savings. These principles act as your compass, guiding your decisions and helping you stay on track towards your 7% growth target.
Principle 1: Diversification is Your Best Defense
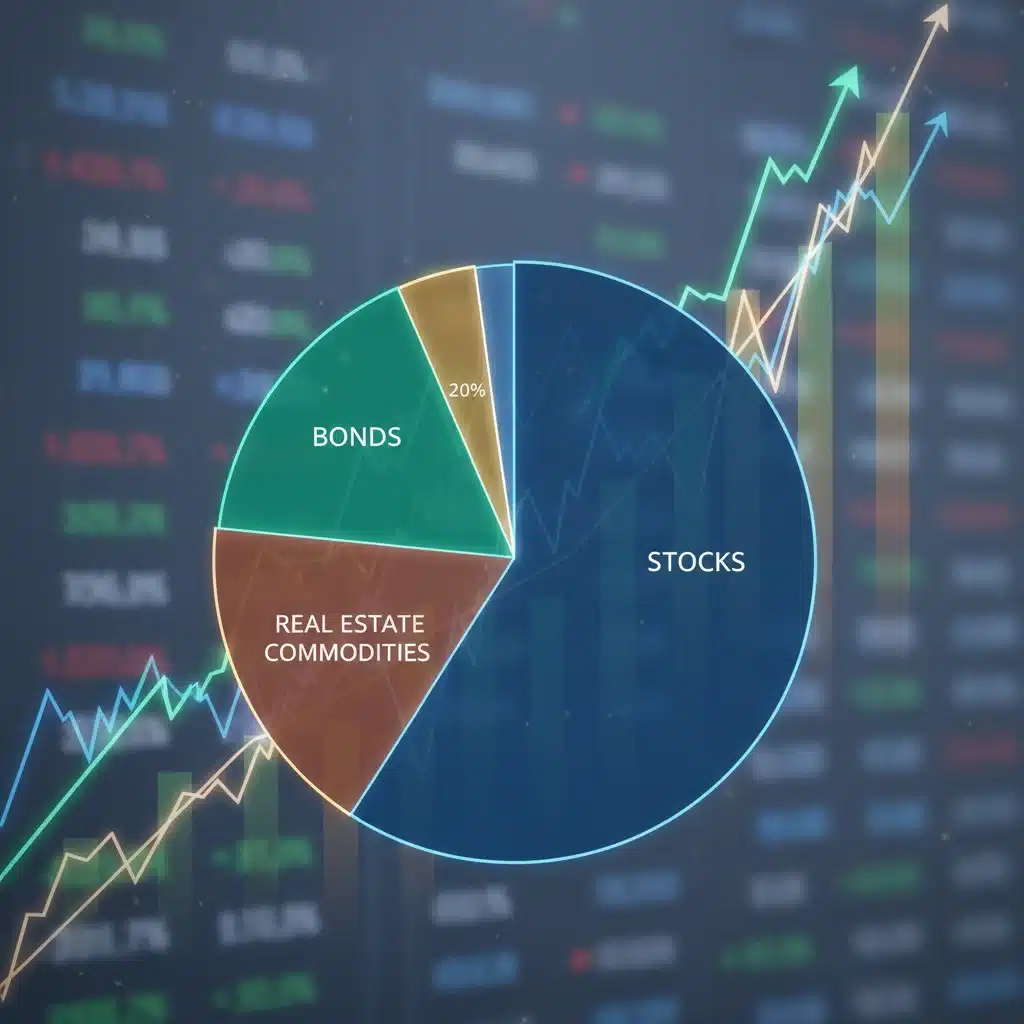
Putting all your eggs in one basket is a risky endeavor, especially when battling inflation. Diversification across different asset classes, industries, and geographies is paramount. When one sector or asset class underperforms due to inflationary pressures, others may perform well, balancing out your overall portfolio. A truly diversified portfolio helps to inflation proof savings by spreading risk and capturing growth opportunities wherever they arise.
Principle 2: Real Assets vs. Financial Assets
During periods of high inflation, real assets often perform better than financial assets. Real assets include tangible items like real estate, commodities (gold, silver, oil), and infrastructure. Financial assets, on the other hand, are typically paper assets like stocks, bonds, and cash. Real assets tend to hold their value or even appreciate during inflationary periods because their intrinsic value is tied to physical resources, which become more expensive as inflation rises. Understanding this distinction is key to building a portfolio that can inflation proof savings effectively.
Advertisement
Principle 3: Income-Generating Investments
Investments that generate regular income can be a powerful tool against inflation. Dividends from stocks, rental income from real estate, or interest from certain bonds provide a consistent cash flow that can help offset the rising cost of living. Reinvesting this income can further compound your returns, accelerating your journey to inflation proof savings and reaching that 7% growth target.
Principle 4: Long-Term Perspective
Financial markets are inherently volatile in the short term. Trying to time the market or react to every economic fluctuation is often counterproductive. A long-term perspective, focusing on your 2026 goal, allows you to ride out temporary downturns and benefit from the power of compounding. Patience and discipline are essential when you aim to inflation proof savings over several years.
Strategic Investments to Achieve 7% Growth by 2026
Now, let’s explore specific investment vehicles and strategies that can help you inflation proof savings and achieve your 7% annual growth target. Remember, the optimal mix will depend on your individual risk tolerance, financial situation, and time horizon.
1. Real Estate: A Tangible Hedge Against Inflation
Real estate has historically been an excellent hedge against inflation. As the cost of building materials and labor rises, so does the value of existing properties. Rental income also tends to increase with inflation, providing a growing income stream. There are several ways to invest in real estate:
- Direct Property Ownership: Buying residential or commercial properties can provide both appreciation and rental income. This requires significant capital and management effort, but can be highly rewarding.
- Real Estate Investment Trusts (REITs): REITs are companies that own, operate, or finance income-generating real estate. They trade on stock exchanges like stocks and offer a way to invest in real estate without directly owning property. REITs are often required to distribute a significant portion of their income to shareholders, providing attractive dividends.
- Real Estate Crowdfunding: Platforms allow you to invest in a share of a larger real estate project with smaller amounts of capital, diversifying your real estate exposure.
When considering real estate to inflation proof savings, focus on markets with strong demand, limited supply, and potential for rental growth.
2. Commodities: Raw Materials for Inflationary Times
Commodities are raw materials or primary agricultural products that can be bought and sold, such as gold, oil, natural gas, and agricultural products. Their prices often rise during inflationary periods because they are the basic inputs for goods and services, which become more expensive. Including commodities in your portfolio can significantly help to inflation proof savings.
- Gold: Often considered a safe-haven asset, gold tends to perform well when inflation is high or when there is economic uncertainty. It acts as a store of value.
- Energy Commodities (Oil, Natural Gas): As energy costs are a significant driver of inflation, investments in energy-related commodities or companies can provide a hedge.
- Agricultural Commodities: Prices for food staples can also rise with inflation, making agricultural commodities an interesting consideration.
You can gain exposure to commodities through exchange-traded funds (ETFs) that track commodity indices or through futures contracts (though futures are generally for more experienced investors).
3. Treasury Inflation-Protected Securities (TIPS): Direct Inflation Protection
TIPS are U.S. Treasury bonds that are indexed to inflation to protect investors from a decline in the purchasing power of their money. The principal value of TIPS adjusts with the Consumer Price Index (CPI), and interest payments are made on the adjusted principal. When CPI rises, the principal value of TIPS increases, and vice versa. This direct link makes TIPS an excellent tool to inflation proof savings.
- How they work: If inflation rises, the principal value of your TIPS increases, and your semi-annual interest payments, which are a fixed percentage of the principal, also increase. At maturity, you receive either the adjusted principal or the original principal, whichever is greater.
- Benefits: They offer guaranteed protection against inflation and are backed by the full faith and credit of the U.S. government, making them very low risk.
TIPS can be purchased directly from the U.S. Treasury or through mutual funds and ETFs.
4. Dividend-Paying Stocks: Growing Income Stream
Companies that consistently pay and grow their dividends can offer a dual benefit: potential capital appreciation and a rising income stream. Strong, established companies with a history of increasing dividends often have pricing power, allowing them to pass on higher costs to consumers during inflationary periods. This makes them attractive for those looking to inflation proof savings.
- Focus on Dividend Aristocrats/Kings: These are companies that have consistently increased their dividends for 25 or 50+ consecutive years, respectively. They tend to be stable, financially sound businesses.
- Sectors to Consider: Consumer staples, utilities, healthcare, and certain industrial sectors often house strong dividend payers.
Reinvesting these dividends can significantly accelerate your wealth accumulation through compounding, helping you reach that 7% growth target faster.
5. Value Stocks: Overlooked Potential
Value stocks are shares of companies that appear to trade for less than their intrinsic value. These are often mature companies with stable earnings and strong balance sheets that may be temporarily out of favor with the market. During inflationary periods, investors often gravitate towards tangible assets and companies with strong fundamentals, making value stocks potentially attractive. They can be a key component in strategies to inflation proof savings.
- Why they work: Value companies often have established market positions and pricing power, allowing them to maintain profitability even as costs rise. Their lower valuations also offer a margin of safety.
- Research is Key: Identifying true value stocks requires careful analysis of financial statements, competitive advantages, and management quality.
6. Alternative Investments: Beyond Traditional Markets
For accredited investors or those with higher risk tolerance, alternative investments can offer unique opportunities to inflation proof savings and enhance returns.
- Private Equity/Debt: Investing in private companies or providing debt financing can offer higher returns than public markets, often with less correlation to traditional asset classes.
- Infrastructure Funds: Investments in essential services like roads, bridges, and utilities often have stable, inflation-linked cash flows.
- Cryptocurrencies (with caution): While highly volatile, some view Bitcoin as a potential digital gold, a hedge against traditional fiat currency inflation. However, its volatility means it should only be considered a small, speculative portion of a well-diversified portfolio.
Financial Planning Strategies to Support Your Goal
Beyond specific investments, several financial planning strategies are crucial to effectively inflation proof savings and hit your 7% growth target by 2026.
1. Maximize Tax-Advantaged Accounts
Utilize retirement accounts like 401(k)s, IRAs, and HSAs. These accounts offer tax benefits (tax-deferred growth or tax-free withdrawals) that can significantly boost your net returns over time, making it easier to inflation proof savings without the drag of annual taxes on gains.
- 401(k) and IRA: Contributions grow tax-deferred, and some offer tax deductions upfront.
- Health Savings Account (HSA): Offers a triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. This is often considered one of the most powerful savings vehicles.
2. Regular Portfolio Rebalancing
As your investments grow and market conditions change, your portfolio allocation will drift from its original targets. Regular rebalancing (e.g., annually or semi-annually) involves selling assets that have performed well and buying those that have underperformed to bring your portfolio back to your desired allocation. This disciplined approach helps maintain your risk profile and ensures you continue to inflation proof savings effectively.
3. Debt Management
High-interest debt can quickly eat into your savings and investment returns. Prioritizing the repayment of consumer debt (credit cards, personal loans) is a critical step. While inflation can erode the real value of fixed-rate debt, the interest payments still represent a significant drain on your cash flow that could otherwise be invested. Managing debt effectively frees up capital to help you inflation proof savings and invest more aggressively.
4. Emergency Fund Review
Ensure your emergency fund is adequate, typically 3-6 months of living expenses. However, in an inflationary environment, the *amount* needed for these expenses will increase. Regularly review and adjust your emergency fund to ensure it can still cover your needs, even as costs rise. While an emergency fund typically sits in low-yield accounts, it provides the essential liquidity and peace of mind necessary to take on calculated investment risks to inflation proof savings in your long-term portfolio.
5. Continuous Learning and Adaptation
The economic landscape is dynamic. What works today might not be optimal tomorrow. Stay informed about economic trends, inflation data, and market developments. Be willing to adapt your strategies as needed. Reading financial news, consulting with financial advisors, and continuously educating yourself will empower you to make informed decisions to inflation proof savings effectively over the long term.
Monitoring Your Progress Towards 7% Growth
Setting a goal to inflation proof savings and achieve 7% growth by 2026 is only half the battle; the other half is diligent monitoring and adjustment. Regular reviews of your portfolio’s performance against your target are essential.
1. Track Your Net Worth
Beyond individual investment returns, tracking your overall net worth (assets minus liabilities) provides a holistic view of your financial progress. Use personal finance software or spreadsheets to regularly update your net worth. This helps you see the combined effect of your savings, investments, and debt reduction efforts, and whether you are successfully working to inflation proof savings on a broader scale.
2. Calculate Real Rate of Return
To truly understand if you are inflation proof savings, you need to calculate your real rate of return. This is your nominal return minus the inflation rate. If your nominal return is 7% and inflation is 3%, your real return is 4%. Your goal is to keep this real return positive and as high as possible. This metric is crucial for assessing the effectiveness of your strategies to inflation proof savings.
3. Review Investment Performance
Periodically review the performance of each of your investments. Are they meeting expectations? Are there underperforming assets that need to be re-evaluated? While a long-term perspective is key, consistent underperformance without a clear rationale may warrant a change. This is part of the iterative process of ensuring you inflation proof savings effectively.
4. Stay Informed on Economic Indicators
Keep an eye on key economic indicators such as the Consumer Price Index (CPI), Producer Price Index (PPI), interest rates, and GDP growth. These indicators can provide clues about future inflationary pressures and help you anticipate potential impacts on your portfolio. Being proactive rather than reactive is a hallmark of successful strategies to inflation proof savings.
Challenges and Considerations
While the goal of 7% growth is achievable, it’s important to acknowledge potential challenges and considerations:
- Market Volatility: Markets will always have ups and downs. Stick to your long-term plan and avoid emotional decisions.
- Unexpected Inflation Spikes: While we aim to inflation proof savings, extreme, unforeseen spikes in inflation can still impact returns. Diversification and flexibility are your best defenses.
- Interest Rate Changes: Rising interest rates can impact bond prices and borrowing costs, influencing investment decisions.
- Personal Circumstances: Life events like job loss, health issues, or family changes can impact your ability to save and invest. Having an emergency fund and insurance coverage can mitigate these risks.
Conclusion: Your Path to Inflation-Proofed Prosperity by 2026
Achieving a 7% annual growth rate on your savings by 2026 while simultaneously working to inflation proof savings is an ambitious yet entirely attainable goal. It requires a combination of strategic investment choices, disciplined financial planning, and continuous monitoring. By understanding the principles of inflation protection, diversifying across real assets, income-generating investments, and tax-advantaged accounts, you can build a robust portfolio designed to withstand economic pressures and grow your wealth significantly.
Start today by assessing your current financial situation, defining your risk tolerance, and gradually implementing the strategies outlined in this guide. Remember, consistency and patience are your greatest allies on this journey. With a clear vision and a well-executed plan, you can confidently navigate the economic landscape and emerge with your savings not just protected, but thriving, by 2026. Take control of your financial future and actively work to inflation proof savings for lasting prosperity.