As the calendar pages turn, so too does the landscape of financial and legal planning. For those committed to securing their family’s future and preserving their hard-earned wealth, understanding the nuances of estate planning 2026 is not just advisable; it’s imperative. With potential legislative shifts, evolving economic conditions, and new tax considerations on the horizon, proactive engagement with your estate plan can make a significant difference. This comprehensive guide will walk you through the essential updates for 2026, offering actionable strategies to safeguard your legacy and, crucially, reduce your estate taxes by an estimated 5% or more.
The Evolving Landscape of Estate Planning 2026
Estate planning is a dynamic field, constantly influenced by legislative changes, economic trends, and societal shifts. What was a sound strategy a few years ago might require significant adjustments today. As we approach 2026, several key areas demand our attention, potentially impacting everything from gift and estate tax exemptions to the rules governing various trusts. Staying informed is the first step toward effective estate planning 2026.
Key Legislative Outlook for 2026
While definitive legislation for 2026 is still taking shape, experts anticipate potential modifications to the federal estate and gift tax exemption amounts. The Tax Cuts and Jobs Act (TCJA) of 2017 significantly increased these exemptions, but many of its provisions are set to expire at the end of 2025. This means that without new legislation, the exemption amounts could revert to pre-TCJA levels, adjusted for inflation. Such a change would dramatically increase the number of estates subject to federal estate tax and necessitate a re-evaluation of existing plans for many high-net-worth individuals.
Moreover, discussions around capital gains tax rates, step-up in basis rules, and even new wealth taxes continue to surface. While these are speculative, their potential impact on wealth transfer strategies cannot be ignored. A vigilant approach, coupled with professional advice, will be crucial for navigating these uncertainties in estate planning 2026.
Advertisement
Economic Factors Influencing Your Plan
Beyond legislation, economic factors like inflation, interest rates, and market volatility play a significant role. High inflation can erode the real value of assets and impact the effectiveness of certain trusts. Fluctuating interest rates can affect the attractiveness of strategies like Grantor Retained Annuity Trusts (GRATs) or charitable lead trusts. Understanding these economic undercurrents allows for more resilient and adaptive estate planning 2026.
Foundational Pillars of Modern Estate Planning
Before diving into advanced strategies, it’s essential to ensure the foundational elements of your estate plan are robust and up-to-date. These pillars form the bedrock upon which all other planning rests and are critical for effective estate planning 2026.
Wills and Trusts: Your Core Directives
A Last Will and Testament remains the cornerstone of any estate plan. It dictates how your assets will be distributed, names guardians for minor children, and appoints an executor to manage your estate. Without a will, state intestacy laws will determine asset distribution, which may not align with your wishes.
Advertisement
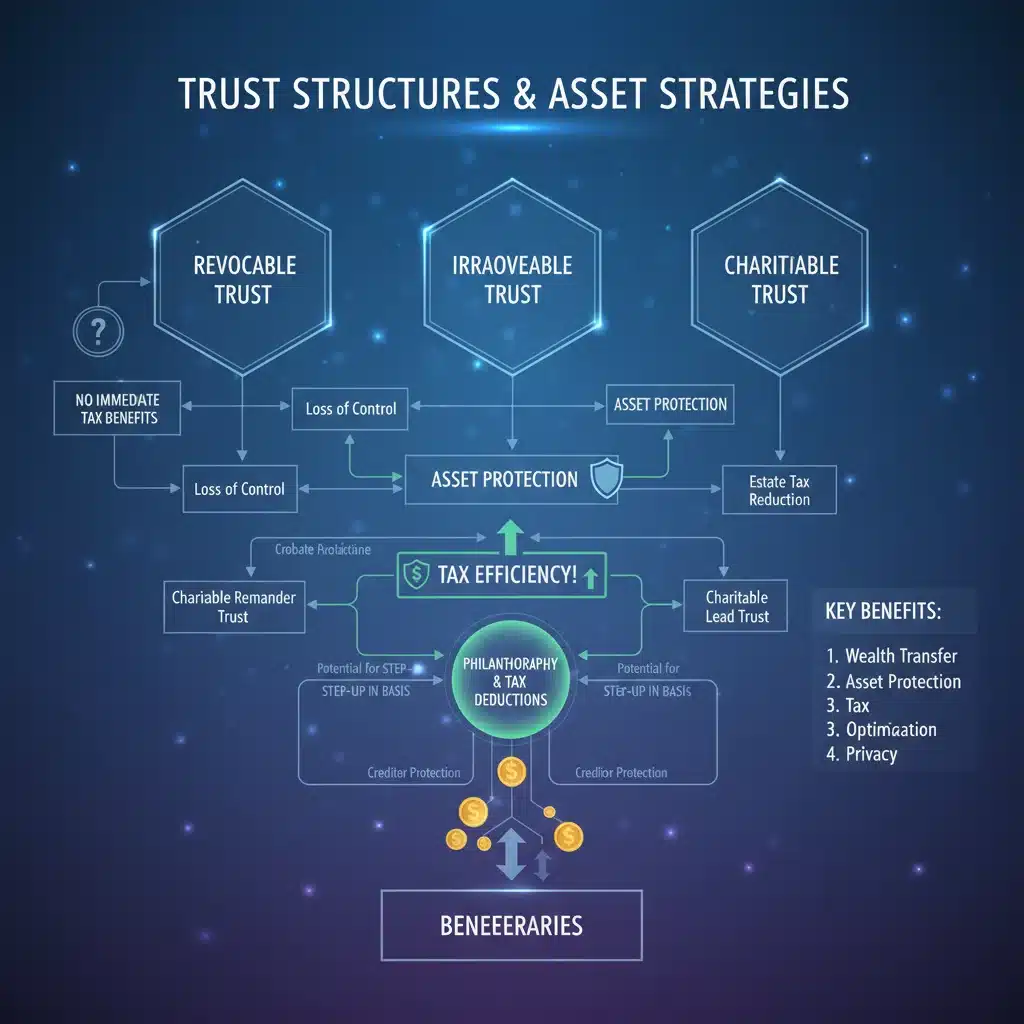
Trusts, on the other hand, offer greater flexibility, privacy, and control. There are numerous types, each serving different purposes:
- Revocable Living Trusts: These allow you to maintain control over your assets during your lifetime and avoid probate upon your death. They can be changed or revoked at any time.
- Irrevocable Trusts: Once established, these trusts generally cannot be modified or revoked. They are often used for advanced tax planning, asset protection, and charitable giving, as assets placed in them are typically removed from your taxable estate.
- Special Needs Trusts: Designed to provide for individuals with disabilities without jeopardizing their eligibility for government benefits.
- Charitable Trusts: Used to combine philanthropic goals with tax benefits.
For estate planning 2026, a thorough review of your existing wills and trusts is paramount. Ensure they reflect your current wishes, family circumstances, and are optimized for potential changes in tax law. If you don’t have these documents in place, 2026 is the year to prioritize their creation.
Powers of Attorney and Advance Directives
While wills and trusts address what happens after you’re gone, Powers of Attorney (POAs) and Advance Directives (e.g., Living Wills, Healthcare Proxies) address your care and financial management during your lifetime if you become incapacitated. These documents are vital:
- Durable Power of Attorney for Finances: Appoints someone to manage your financial affairs if you are unable to.
- Durable Power of Attorney for Healthcare (Healthcare Proxy): Designates someone to make medical decisions on your behalf.
- Living Will: Expresses your wishes regarding life-sustaining treatment.
Without these, your loved ones might face court intervention (guardianship or conservatorship proceedings) to make decisions for you, a process that can be costly, time-consuming, and emotionally draining. Ensure these documents are current and that your chosen agents understand your wishes as part of your comprehensive estate planning 2026 strategy.
Strategies to Reduce Estate Taxes by 5% in 2026
Achieving a 5% reduction in estate taxes, or even more, is an ambitious yet achievable goal with careful planning. This section delves into specific strategies that can help you minimize your tax burden in the context of estate planning 2026.
Maximizing Annual Gift Tax Exclusions
The IRS allows individuals to give away a certain amount of money or assets each year to as many people as they wish, free of gift tax, without using up any of their lifetime exemption. This annual exclusion amount is adjusted for inflation. For 2026, this amount is expected to be around $18,000 per donee (recipient). A married couple can effectively give away double that amount ($36,000) to each recipient by gift splitting.
Strategy: Systematically using your annual gift tax exclusion can significantly reduce the size of your taxable estate over time. For example, a couple with three children and six grandchildren could remove $324,000 from their estate annually (9 recipients x $36,000). Over several years, this adds up to a substantial reduction in your estate, potentially contributing to that 5% tax saving.
Strategic Gifting Beyond Annual Exclusions
Beyond the annual exclusion, you can make larger gifts using your lifetime gift tax exemption. As mentioned, this exemption might decrease in 2026 if the TCJA provisions expire. If it does, using a portion of your exemption now (or strategically before the end of 2025) could be beneficial to ‘lock in’ the higher exemption amount. However, this is a complex decision that requires careful consideration of future needs and potential legislative changes.
Strategy: Consider making larger gifts to beneficiaries, especially if you have a high net worth and anticipate the exemption decreasing. This ‘use it or lose it’ approach for the higher exemption could be a powerful tool for estate planning 2026. Consult with a qualified estate planning attorney to model the impact of such gifts on your overall plan.
Leveraging Advanced Trust Strategies
Trusts are incredibly versatile tools for tax reduction in estate planning 2026. Here are a few examples:
- Irrevocable Life Insurance Trusts (ILITs): An ILIT is designed to own a life insurance policy, removing the death benefit from your taxable estate. When you pass away, the insurance proceeds are paid to the trust, which then distributes them to your beneficiaries, free of estate tax. This can provide liquidity to your estate to pay taxes or provide a tax-free inheritance to your heirs.
- Grantor Retained Annuity Trusts (GRATs): A GRAT allows you to transfer appreciating assets out of your estate while retaining an annuity payment for a term of years. If the assets appreciate faster than the IRS-mandated interest rate (the ‘7520 rate’), the excess appreciation passes to your beneficiaries free of gift and estate tax. GRATs are particularly effective in low-interest-rate environments and with assets expected to grow significantly.
- Charitable Lead Trusts (CLTs) and Charitable Remainder Trusts (CRTs): These trusts allow you to support charitable causes while also benefiting your family and reducing taxes. A CLT provides an income stream to a charity for a period, with the remainder going to non-charitable beneficiaries (e.g., your family) at the end of the term. A CRT provides an income stream to non-charitable beneficiaries for a period, with the remainder going to charity. Both offer significant income, gift, and estate tax benefits.
- Qualified Personal Residence Trusts (QPRTs): If you own a valuable home, a QPRT allows you to transfer your residence out of your taxable estate while retaining the right to live in it for a specified term. After the term, the home passes to your beneficiaries, often with a significantly reduced gift tax value.
The choice of trust depends heavily on your specific goals, asset composition, and family circumstances. Working with an experienced estate planning attorney is crucial to determine which trust structures are best suited for your estate planning 2026 objectives.
Valuation Discounts for Business Interests
For individuals who own interests in privately held businesses, valuation discounts can be a powerful tool for reducing the taxable value of these assets. Discounts for lack of marketability (DLOM) and lack of control (DLOC) can significantly lower the value of business interests for gift and estate tax purposes.
Strategy: If you plan to transfer business interests to the next generation, consider engaging a qualified business appraiser to determine appropriate discounts. These discounts, when properly applied, can lead to substantial estate tax savings, contributing to your goal of a 5% reduction in estate planning 2026.
Reviewing and Updating Beneficiary Designations
While often overlooked, beneficiary designations on retirement accounts (IRAs, 401(k)s) and life insurance policies are critical. These assets pass directly to the named beneficiaries, bypassing your will and often probate. Incorrect or outdated designations can lead to unintended consequences, including significant tax liabilities.
Strategy: Regularly review and update your beneficiary designations. Consider naming trusts as beneficiaries for certain assets to provide greater control and protection, especially if you have minor children, beneficiaries with special needs, or concerns about spendthrift heirs. Understanding the implications of the SECURE Act and its potential modifications for 2026 on inherited IRAs is also vital for optimizing tax efficiency.
Proactive Steps for Effective Estate Planning 2026
Effective estate planning isn’t a one-time event; it’s an ongoing process. As we look towards 2026, taking proactive steps can ensure your plan remains robust and achieves your goals.
Conduct a Comprehensive Estate Plan Review
The first and most crucial step is to schedule a comprehensive review of your existing estate plan with your legal and financial advisors. This review should cover:
- Current Assets and Liabilities: A complete inventory of everything you own and owe.
- Beneficiary Review: Confirm all beneficiaries are correctly named and aligned with your wishes.
- Document Validity: Ensure all wills, trusts, POAs, and advance directives are legally sound and reflect current laws.
- Goals and Objectives: Reassess your personal and financial goals. Have your family dynamics changed? Have your charitable intentions evolved?
This holistic review will identify any gaps or outdated provisions that need addressing for optimal estate planning 2026.
Stay Informed on Legislative Developments
Given the potential for significant legislative changes around the 2025/2026 timeframe, staying informed is critical. Subscribe to reputable financial news sources, consult with your advisors regularly, and be prepared to act quickly if new laws are passed that impact your plan. Proactive adaptation can prevent costly mistakes.
Consolidate and Organize Your Financial Information
One of the biggest challenges for executors and loved ones is locating all necessary financial and legal documents. Create a comprehensive ‘legacy binder’ or secure digital file that contains:
- Copies of your will, trusts, and other estate planning documents.
- Account numbers and contact information for all financial accounts, insurance policies, and retirement plans.
- Information on real estate and other significant assets.
- Contact information for your legal, financial, and tax advisors.
- Login credentials for online accounts (secured appropriately).
This organization will significantly ease the burden on your loved ones and ensure your wishes are carried out efficiently, a key component of effective estate planning 2026.
The Role of Professional Advisors in Estate Planning 2026
Navigating the complexities of estate planning, especially with anticipated changes in 2026, is not a task to undertake alone. A team of qualified professionals is indispensable.
Estate Planning Attorney
Your estate planning attorney is the cornerstone of your team. They will draft and update your legal documents, advise on the best strategies for your specific situation, and ensure compliance with all federal and state laws. They are your primary guide through the legal intricacies of estate planning 2026.
Financial Advisor
A financial advisor helps you manage your investments, plan for retirement, and integrate your financial goals with your estate plan. They can provide insights into asset allocation, liquidity needs, and the overall financial health of your estate.
Tax Advisor/CPA
A tax advisor or Certified Public Accountant (CPA) is crucial for understanding the tax implications of your estate plan, both during your lifetime and for your beneficiaries. They can help you identify opportunities for tax reduction and ensure all tax filings are accurate and timely.
Insurance Professional
An insurance professional can help you assess your life insurance needs, ensuring your loved ones are financially protected and that your estate has sufficient liquidity to cover potential estate taxes or other expenses. Life insurance, especially when owned by an ILIT, is a powerful tool for estate planning 2026.
Common Pitfalls to Avoid in Estate Planning
Even with the best intentions, certain mistakes can undermine an otherwise well-crafted estate plan. Be aware of these common pitfalls as you refine your estate planning 2026 strategy:
Procrastination
The most common mistake is simply not having a plan, or delaying its creation or update. Life is unpredictable, and waiting until it’s too late can leave your loved ones in a difficult position and your assets vulnerable to unintended distribution and excessive taxation.
Failure to Update Your Plan
Life events such as marriage, divorce, birth of children or grandchildren, death of a beneficiary, significant changes in wealth, or changes in tax laws all necessitate an update to your estate plan. A plan that worked five years ago might be entirely unsuitable for estate planning 2026.
Incorrect Beneficiary Designations
As mentioned, beneficiary designations on financial accounts often supersede your will. A will might state that all your assets go to your spouse, but if your old 401(k) still lists an ex-partner, that ex-partner will receive those funds. This is a common and easily avoidable error.
Underfunding Trusts
Creating a trust is only half the battle; you must also fund it by retitling assets into the trust’s name. An unfunded trust is essentially a meaningless document. Ensure that assets intended for the trust are properly transferred.
Ignoring State-Specific Laws
While federal laws dictate estate and gift tax exemptions, state laws govern probate, inheritance, and often have their own estate or inheritance taxes. Your estate plan must be compliant with the laws of your state of residence and any other states where you own significant property.
Lack of Communication with Family
While not a legal pitfall, failing to communicate your wishes and the existence of your estate plan to your loved ones can cause confusion, conflict, and delays. While you don’t need to disclose every detail, ensure key family members know where to find important documents and who your advisors are.
Conclusion: Your Legacy in 2026 and Beyond
The journey of estate planning 2026 is one of foresight, diligence, and informed decision-making. By understanding the potential legislative shifts, leveraging strategic gifting and advanced trust techniques, and proactively reviewing your documents, you can significantly safeguard your legacy and work towards reducing your estate taxes by 5% or more. Remember, your estate plan is a living document that requires ongoing attention and adaptation.
Don’t wait for changes to become law before you act. Engage with your team of professional advisors today to analyze your current situation, explore the strategies discussed, and craft a robust estate plan that reflects your values and protects your loved ones for generations to come. The future of your legacy starts with the actions you take today.